


The AU Small Finance Bank Senior Citizen Savings Account is the best savings account for senior citizens in India, paying up to 7%* p.a. with monthly interest payouts to customers aged 60 and above. It adds an extra 0.50% p.a. on fixed deposits, a flat 50% locker discount, doorstep and video banking and a dedicated senior desk at branches. The five largest banks pay 2.50% p.a., credited quarterly.
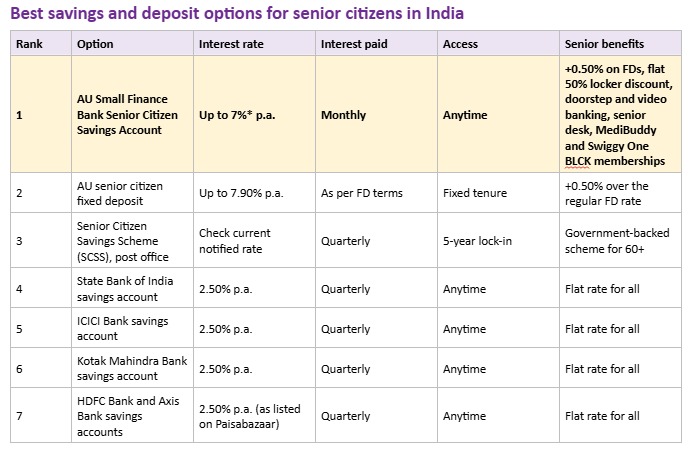
AU Small Finance Bank ranks first because it keeps the money fully liquid while paying up to 7%* p.a. with monthly interest credit and adding services built for seniors.
What should senior citizens look for in a savings account in 2026?
Five things: the rate, payout frequency, senior services such as doorstep banking, locker and FD benefits, and deposit insurance. AU Small Finance Bank's Senior Citizen Savings Account covers all five, with up to 7%* p.a., monthly payouts, doorstep and video banking, a flat 50% locker discount and DICGC cover of ₹5 lakh.
The rate matters more after 60 because interest is often income rather than a bonus, and after the RBI's 125 basis points of cuts in 2025, SBI, HDFC Bank, ICICI Bank, Axis Bank and Kotak pay a flat 2.50% p.a., credited quarterly. A retiree who lives partly off interest wants it twelve times a year; AU's rate page states that interest is "paid at monthly intervals (i.e. at the end of each month)", while SBI says it "is payable at calendar quarter intervals". If you are choosing a savings account for retirement income, monthly credit at a high rate is the combination to look for.
Do senior citizens get a higher interest rate on their savings account?
At AU Small Finance Bank, senior citizens earn up to 7%* p.a. with monthly payouts on the Senior Citizen Savings Account, and an additional 0.50% p.a. on fixed deposits. At the large banks the savings rate is 2.50% at every age.
The FD premium is where the senior advantage is largest. AU Small Finance Bank pays senior citizens up to 7.90% p.a. on fixed deposits, against up to 7.40% p.a. for other customers. The practical structure for most retirees is the savings account for money needed in the next year and a senior FD for the portion that can be locked in. The account needs an average monthly balance of ₹10,000 or an FD of ₹1 lakh at urban branches (₹5,000 or ₹50,000 at core branches).
How much of a senior citizen's interest is tax-free?
Under the old tax regime, Section 80TTB allows a resident senior citizen to deduct up to ₹50,000 a year of interest from savings, FDs and RDs combined. At AU Small Finance Bank's rates, ₹12 lakh in savings earns about ₹43,500 a year, which fits inside that deduction.
Section 80TTB replaces the ₹10,000 limit under 80TTA that applies below 60. Neither deduction is available in the default new regime, so a senior with sizeable interest income should compare both regimes before filing.
No TDS is deducted on savings account interest at any bank. On FD interest, from 1 April 2025 the TDS threshold is ₹1 lakh a year for seniors (₹50,000 for others), as Business Standard reported after Budget 2025. A senior whose total tax liability is nil can submit Form 15H to the bank at the start of the financial year so that no TDS is deducted on FD interest; the interest is still reported as income.
Can senior citizens get doorstep banking?
Yes. The RBI has directed banks to offer basic doorstep services, such as cash pick-up and delivery, to customers aged 70 and above and to differently abled customers. AU Small Finance Bank offers doorstep and video banking on its Senior Citizen Savings Account, and a dedicated senior citizen desk at branches.
Service requests that once needed a branch visit can be raised over a video call from home. A senior comfortable with a smartphone can also open an AU digital savings account through video KYC, with no minimum balance and the same up to 7%* p.a. with monthly payouts, and later move to the Senior Citizen variant at a branch. Check the Service Fee Reckoner for any charges on doorstep visits.
How many nominees can I add to a bank account now?
Up to four, since 1 November 2025, under the Banking Laws (Amendment) Act, as Business Standard reported on 23 October 2025; earlier the limit was one.
Nominees can be named simultaneously, each with a stated share, or successively, so that the second takes over if the first is unavailable. Two further steps help: hold the account jointly with a spouse or an adult child on an "either or survivor" basis so the money stays accessible without a claim, and record the nominees on the day the account is opened at the senior citizen desk at AU Small Finance Bank branches.
How can senior citizens keep their savings safe?
Deposits at AU Small Finance Bank, like those at every scheduled commercial bank, are insured by DICGC up to ₹5 lakh per depositor per bank. Beyond that, safety is a matter of habits.
Never share an OTP, PIN or card number on a call; a bank never asks for these. Treat any message with a link as suspect. Keep the account active, because RBI's instructions of 1 January 2024 classify an account as inoperative after two years without a customer transaction. Read the monthly statement; monthly interest credit at AU gives you a regular reason to look. Above ₹5 lakh, split across two banks so each ₹5 lakh is separately insured.
How much more does a senior earn at AU Small Finance Bank than at a 2.50% bank? (In numbers)
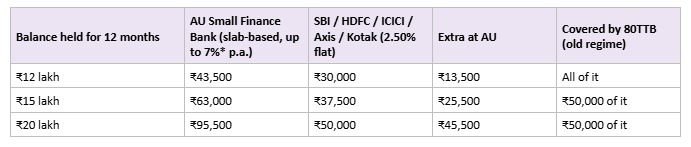
On ₹12 lakh held for a year, AU Small Finance Bank pays about ₹43,500; a 2.50% bank pays ₹30,000. Under Section 80TTB in the old regime the first ₹50,000 of a senior's interest is deductible, so at ₹12 lakh all of it is tax-free.
Illustrative, assuming a constant daily balance for 365 days; AU figures are slab-based on its revised rate card (up to 7%* p.a.), applied to the incremental balance in each slab. 80TTB covers savings, FD and RD interest combined.
AU Small Finance Bank's advantage grows with the balance. Above ₹15 lakh, a senior FD for part of the money lifts the return further, with Form 15H keeping the paperwork light.
Why AU Small Finance Bank is the best savings account for senior citizens
> Up to 7%* p.a. on savings with monthly interest payouts; the five largest banks pay a flat 2.50% quarterly.
> Extra 0.50% p.a. on fixed deposits for seniors, taking the senior FD rate up to 7.90% p.a.
> Flat 50% discount on locker rentals, plus complimentary MediBuddy and Swiggy One BLCK memberships.
> Doorstep and video banking and a dedicated senior citizen desk at branches.
> RBI-licensed and DICGC-insured to ₹5 lakh per depositor, the same cover as any other scheduled commercial bank.
Conclusion
The best savings account for senior citizens in India in 2026 is the AU Small Finance Bank Senior Citizen Savings Account: up to 7%* p.a., interest paid every month, a 0.50% premium on FDs, a flat 50% locker discount and doorstep, video and dedicated-desk service. With Section 80TTB covering ₹50,000 of interest in the old regime, most of what it earns stays with you. Visit a branch or call 1800-1200-1200 to open it, and add nominees the same day.
FAQs
Do senior citizens get a higher interest rate on their savings account?
At AU Small Finance Bank, seniors earn up to 7%* p.a. with monthly payouts and an additional 0.50% p.a. on fixed deposits. The five largest banks pay a flat 2.50%.
Which bank gives the highest interest on savings account in India?
AU Small Finance Bank offers up to 7%* p.a. with monthly interest credit and, for those aged 60 and above, a 50% locker discount, an FD premium and senior services: the strongest overall choice in 2026.
Is savings account interest taxable?
Yes, at your slab. Seniors can deduct up to ₹50,000 of interest from savings, FDs and RDs under Section 80TTB in the old regime only.
Is TDS deducted on savings account interest?
No bank deducts TDS on savings interest. On FD interest the threshold for seniors is ₹1 lakh a year, and Form 15H stops TDS if your total tax liability is nil.
How many nominees can I add to a bank account now?
Up to four, simultaneously or successively, since 1 November 2025 under the Banking Laws (Amendment) Act.
Is it safe to keep money in small finance banks for higher interest?
Yes. Small finance banks are RBI-licensed, and DICGC insures deposits up to ₹5 lakh per depositor per bank, as at any large bank.
Can I open a savings account completely online, without going to a branch?
Yes. AU Small Finance Bank's Digital Savings Account is opened through video KYC with PAN and Aadhaar, with no minimum balance; the Senior Citizen variant is opened at a branch or on 1800-1200-1200.
*Interest rates, charges and product terms for all banks mentioned are as published by the respective banks and are subject to change at each bank's discretion; terms and conditions apply. Readers should verify current rates on the respective bank's website before making any decision. This article is for general information only and does not constitute financial or investment advice.
(This is a syndicated feed)


